Agriculture Business Financing in California
Plan for the costs that arrive before the harvest pays. Financing for California farms, growers, and agricultural businesses—from seasonal operations to equipment upgrades.
Fresno-based. California-wide. Financing subject to lender approval.
Where financing fits
Capital for the season ahead and the operation behind it.
Seasonal operating costs
Review funding for seed, fertilizer, supplies, and other inputs before crop sales are collected.
Farm equipment
Explore loans or leases for tractors, harvest equipment, and other eligible revenue-producing assets.
Labor & harvest expenses
Plan for payroll, contracted services, packing, and transportation around your production and collection cycle.
Operational improvements
Review irrigation equipment, processing upgrades, and facility improvements against useful life and repayment capacity.
Compare financing options.
Choose the structure around the use of funds, repayment capacity, and timing. Availability and terms vary by program.
Agricultural working capital
For eligible operating businesses. Review payment frequency against seasonal receipts; daily or weekly payments may not fit a harvest-based revenue cycle.
Business line of credit
For recurring input purchases and temporary operating gaps, subject to lender review of seasonality, cash flow, and existing obligations.
Farm equipment financing
Loans and leases up to $1M, with terms up to 84 months. A down payment is required; equipment, credit, and business history affect approval.
Commercial receivables financing
Completed sales to eligible commercial buyers may support factoring. Buyer credit, payment rights, quality disputes, and agricultural trust obligations require specific review.
Meet your advisor
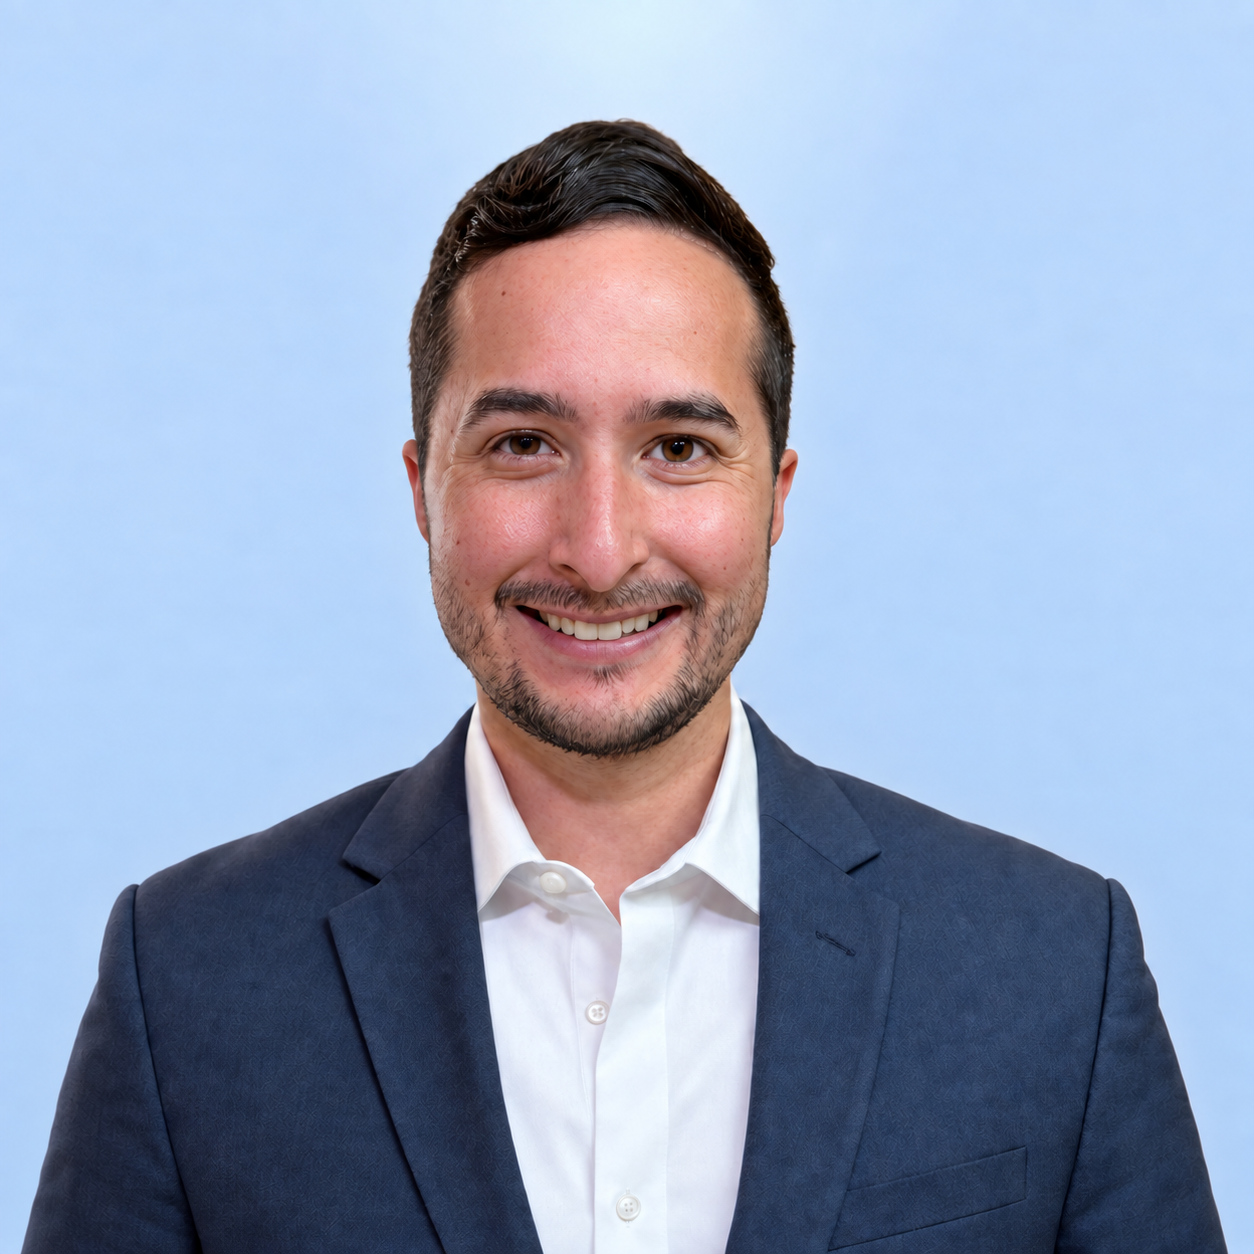
You'll work with Kyle Furtado directly.
I grew up in California's Central Valley, so agriculture isn't an abstraction to me—it's the community I come from. I've seen firsthand how much planning it takes to get a crop from the field to a buyer, and how much capital that takes before the revenue arrives.
Earlier in my financial services career, I specialized in Nationwide's Land As Your Legacy program, working with farm and ranch families on transition and legacy planning. That work taught me how agricultural families think about their land, their equipment, and the next generation—and why the right financing structure matters as much as the rate.
When we review your operation, that background shapes the conversation: seasonal cash flow, equipment cycles, and your long-term plans for the operation.
A practical first review
Start with your business, not a generic offer.
Tell us what you need to fund, when you need it, and how your business collects revenue. We review your situation, identify potential options, and work through the lender's requirements with you.
Operating history, revenue, credit, existing debt, and use of funds all affect eligibility. Startup, acquisition, equipment, and SBA requests have different requirements.
What to have ready
- Business bank statements covering a representative operating cycle
- Financial statements, tax returns, and current debt schedule
- Crop or production schedule and seasonal cash-flow budget
- Equipment quotes and purchase details, when applicable
- Buyer contracts and receivables aging for a receivables review
The documents needed depend on the financing program. Do not submit sensitive records through an unsecured message.
Frequently asked questions
Can financing fit seasonal farm revenue?
Potentially. Lenders review your full revenue cycle, production costs, existing debt, and repayment capacity. Explain when cash arrives; frequent payments are not automatically appropriate for seasonal operations.
Can I finance used farm equipment?
Eligible used equipment may qualify for a loan or lease based on age, condition, vendor, useful life, and your financial profile. A down payment is required.
Can you help with USDA loans?
Yes. We arrange USDA-guaranteed loans, such as FSA guaranteed farm loans and Rural Development Business & Industry loans, through participating lenders. USDA eligibility, limits, and timelines apply, and every loan is subject to lender and agency approval.
Can invoices from produce buyers qualify for factoring?
Some commercial receivables may qualify after review of the buyer, completed sale, payment terms, and assignment rights. Disputes and agricultural trust claims can affect eligibility; a purchase order alone is not a completed receivable.
Let's review your next move.
An equipment purchase, a cash-flow gap, or a larger business investment—start with a conversation.